Postdoctoral Junior Leader Fellowships
Before starting the fellowship
- Career Development Plan
- Ethical issues assessment
- Ethical assessment procedure
- Declaration of interest for the secondment
- Budget Proposal

In such cases, the fellowship period affected by the leave shall be extended by the number of days of the leave. When filling in the justification for this period:
The "la Caixa" Foundation will proceed to modify, accordingly, the periods of the fellowship on the Audit platform, making the fellowship end on the effective date of withdrawal indicated in the letter of resignation.
The institution has a period of 2 months from the effective day of resignation to present the economic justification for the period. Once this has been examined and validated, the "la Caixa" Foundation will send to the institution the settlement form, which will reflect the corresponding amounts as the pro-rated for the number of days of active fellowship.
It should be noted that, in the case of early termination of a Postdoctoral Junior Leader fellowship, the purchase of scientific or IT equipment in the last 3 months preceding the date of resignation cannot be justified. Likewise, other expenses exceeding 1.000€ in the last 3 months preceding the end date must be authorized in advance. Authorization will be required through the "End of fellowship expenses" option in the drop-down menu.For fellows of the calls 2022, 2023 and 2024, there is a limitation:
Fellows of call 2025 onwards are not subject to these rules when transferring remaining research costs from one year to the next
For example:
A fellow is attending a Congress that will take place at the beginning of the second annuity. For this purpose, registration is done and plane tickets are purchased during the first annuity.
As the invoices for such expenses are dated in the first period, they must be justified in the first period, regardless of whether the Congress takes place in the second period.
Please note that eligible activities (conference attendance, traveling for scientific collaboration, etc.) to be covered by the fellowship must take place within the duration of the fellowship (expenses whose invoice date falls within the fellowship period, but which take place after the end of the fellowship, will not be accepted).
Family allowance and mobility allowance are justified separately in the Audit platform. If these allowances have been incorporated as gross amounts in the payroll, the labour costs and corresponding deductions to which they have been subject must be justified in the "Family funds" and "Mobility funds" sections, respectively, and not in the "Hiring costs" subdivision of the "Salary" section.
In relation to the family allowance, it is important to highlight the following differentiation:
The Audit platform does not include overheads by default; it is always the institution that must indicate the amount to be justified in this concept. There is a specific box in the Research costs section of the platform to include the amount corresponding to overheads:
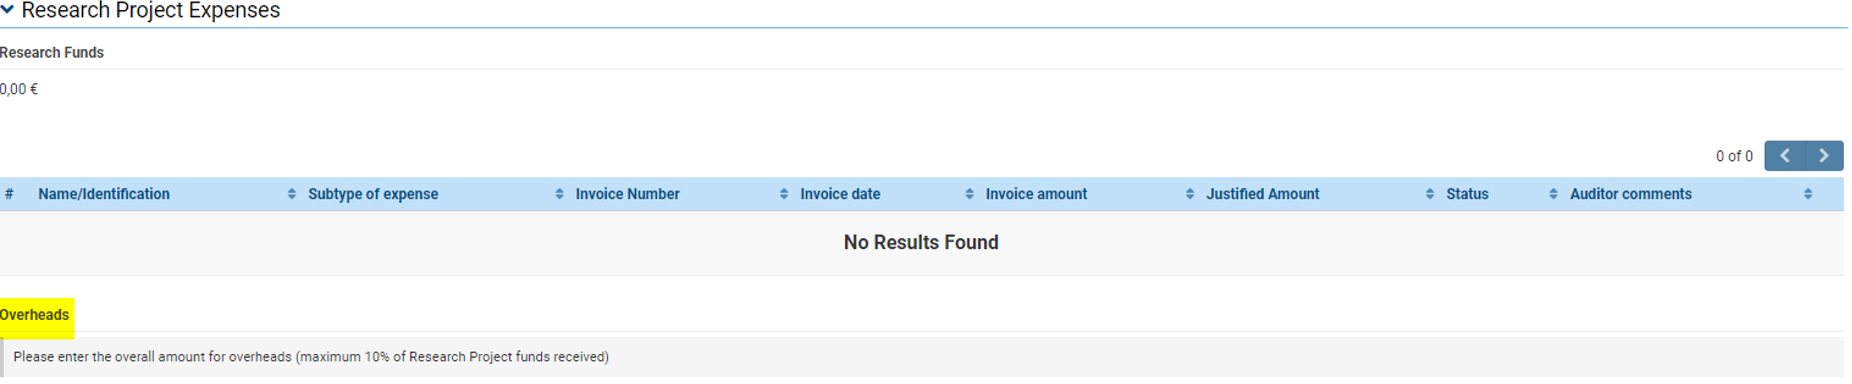
The platform will not request the inclusion of any documentary evidence for overheads.
On the other hand, as the overheads constitute a part of the research costs, in case of a withdrawal it would be necessary to pro-rate exactly how much research costs correspond to the days of active fellowship. Thus, an amount of overheads higher than this pro-rata could not be charged.
Here's an example:
If the fellow resigns having only enjoyed 10 days of the period, the corresponding research costs pro-rata is 1.054,79€, so 3.850€ of overheads could not be justified as it is more than the corresponding research costs.
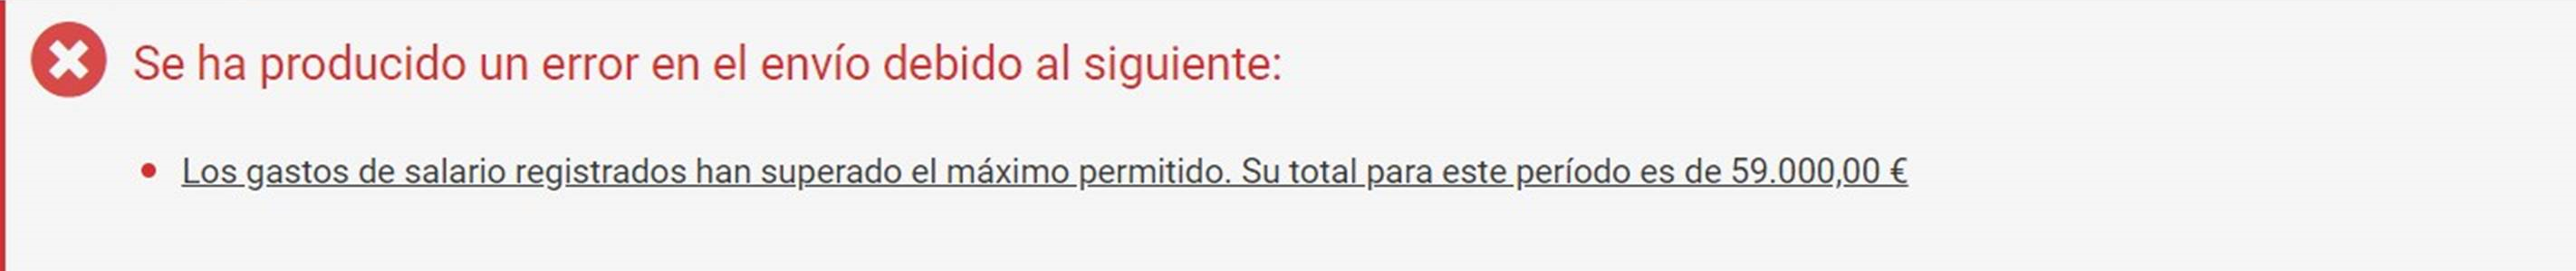
If the institution has had a higher salary expenditure, you should reduce the percentage of dedication of any salary expenditure line so that the total expenditure does not exceed 59.000€, while respecting that the gross salary reflects at least 44.300€, and insert a comment to the auditors explaining this so that they can understand why it has been justified like that.
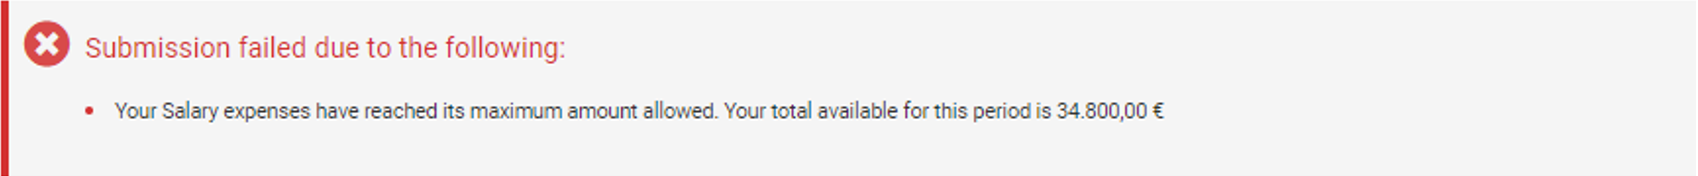
If the institution has had a higher salary expenditure, you should reduce the percentage of dedication of any salary expenditure line so that the total expenditure does not exceed 34.800€, and insert a comment to the auditors explaining this so that they can understand why it has been justified like that.
We remind you that for INPhINIT fellows from call 2024 onwards, the funds awarded in labour costs have been increased to 35.800€. If the institution has had a higher salary expenditure, you should reduce the percentage of dedication of any salary expenditure line so that the total expenditure does not exceed 35.800€, while respecting that the gross salary reflects at least 25.000€, and insert a comment to the auditors explaining this so that they can understand why it has been justified like that.
Continuing with this example, when justifying years 1 and 2, the center could set aside 1.000€ as a provision in each of these years, indicating it in this information box located under the justification of the salary for each period:
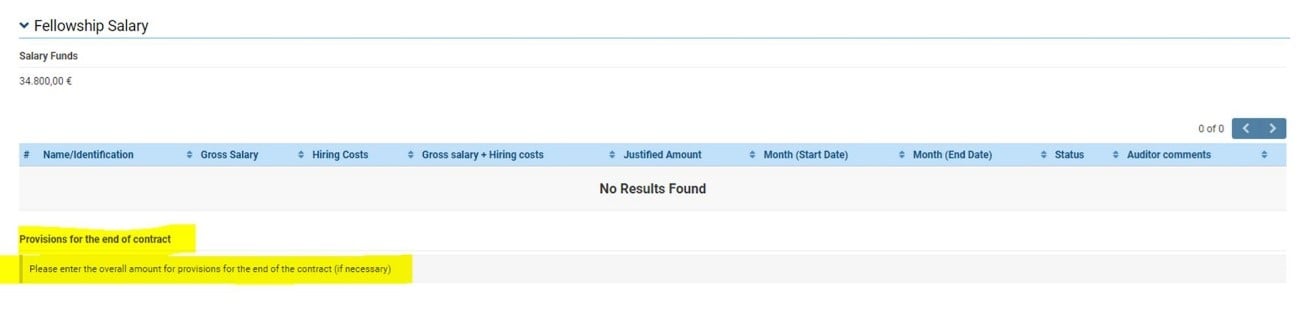
Thus, in in years 1 and 2 the center would provision 2.000€ in total (1.000€+1.000€), and in year 3 the centre will fully justify the 3.000€ as an expense line in the payroll in which the centre pays it.
It is important to note that the minimum gross salary established by each call cannot be affected by the provision.
The same procedure applies to those fellowships lasting 4 years, calculating the pro rata of the compensation for 4 years and provisioning in the 3 first years.
VAT should only be charged in those specific cases where for specific reasons it will not be possible for the institution to deduct the associated VAT, either fully or partially.
Any in-kind economic remuneration, expense compensation or social benefits received by the fellow from the host institution on the basis of the institution's policy, such as meal allowances, restaurant tickets or family allowances, shall not be taken into account for the purposes of calculating the minimum gross annual salary, and must therefore be justified in the Hiring costs section.
If it is possible to include the expense in a subsequent annuity, you can do so by adding an explanatory comment for the auditors so that they can understand why the expense is justified there despite belonging to another annuity based on the invoice date.
If it is not possible to include it in subsequent annuities, please note that from the closure of the justification by the "la Caixa" Foundation, the host institution will have a period of two months to incorporate corrections, bearing in mind that the time exceeded to complete the initial justification is subtracted from the period for corrections.
To this end, the host institution wishing to make corrections must request this by e-mail. If the request is approved, the Audit platform will enable the possibility of incorporating changes in the justification, and the maximum deadline for introducing the corrections will be specified. Once the deadline for corrections has passed, no further changes can be made.
Certain expenses require authorization (either because the Manual itself indicates that they require authorization, or because they are not directly listed as eligible in the Manual).
Requests for authorization must be submitted through the Audit platform before or after the expenditure is incurred. In the latter case, the host institution assumes the risk that the “la Caixa” Foundation may not authorize the allocation of an expense that has already been incurred.
To do this, you must access the "Authorization Request" section on the platform and complete all the fields indicated, with the due justification of the need for the expenditure in the "Comments" section.
In the case of the Doctoral INPhINIT fellowship, the Authorization form must also be attached, duly completed and signed (you will find the template in the repository).
When filling them in, you should bear in mind that:
In the platform you will find explanatory comments next to the different fields to be filled in, which will help you to complete the authorization request.
Payment requests:
PRE-APPROVED BUDGET FOR IT EQUIPMENT
INPhINIT and Junior Leader fellows from call 2025 onwards: within the research costs, a pre-approved budget of 2.500€ is established for the purchase of IT equipment during the fellowship. For these purposes, we consider the following items to be eligible:
Any other IT items not specified in the list will require authorization in order to be charged to the fellowship. Likewise, once the pre-approved budget limit (2.500€) has been exceeded, additional IT equipment may be charged provided that its allocation to the fellowship is authorized by the “la Caixa” Foundation.
Please note that this pre-approved budget is subject to the other restrictions and limitations set out in the guidelines (prohibitions in the last year, end-of-fellowship expenses in Junior Leader, prohibition of more than one computing device with similar functions throughout the INPhINIT fellowship, etc.).
PRE-APPROVED BUDGET FOR SCIENTIFIC EQUIPMENT (INVENTORIABLE)
Junior Leader fellows from call 2025 onwards: within the research costs, a pre-approved budget of 5.000€ is established for the purchase of scientific equipment (inventoriable) in each year (except for year 3), without establishing a list of items directly eligible. Once the pre-approved budget limit has been exceeded (5.000€/year), other scientific equipment may be charged provided that its allocation to the fellowship is authorized by the “la Caixa” Foundation.
Please note that this pre-approved budget is subject to the other restrictions and limitations set out in the guidelines (prohibitions in the last year, end-of-fellowship expenses, etc.).